
Stuart Hansen serves as vice president of Marquee Asset Management, LLC, a Los Angeles-based real estate firm that operates as part of the Drewlo family of companies alongside Drewco Development Corporation. In this role, he oversees domestic and international operations, leading Drewco’s entry into the California real estate market while coordinating with the company’s partners across Asia. Hansen also leads Shelter Asset Management, a newer division of Marquee Asset Management focused on real estate development and investment consulting. Earlier in his career, he served as international investment manager for Drewson Capital Corp and worked in marketing and sales for Clarion Hotels in Canada, eventually advancing to vice president of the Clarion Group of Companies. He holds a business administration degree with honors from the Richard Ivey Business School at the University of Western Ontario. Hansen’s work within the Drewlo family of businesses connects directly to programs like Rent.Save.Own., which link renters to a future home purchase.
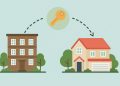
How Drewlo Holdings Connects Renting With Buying a Home
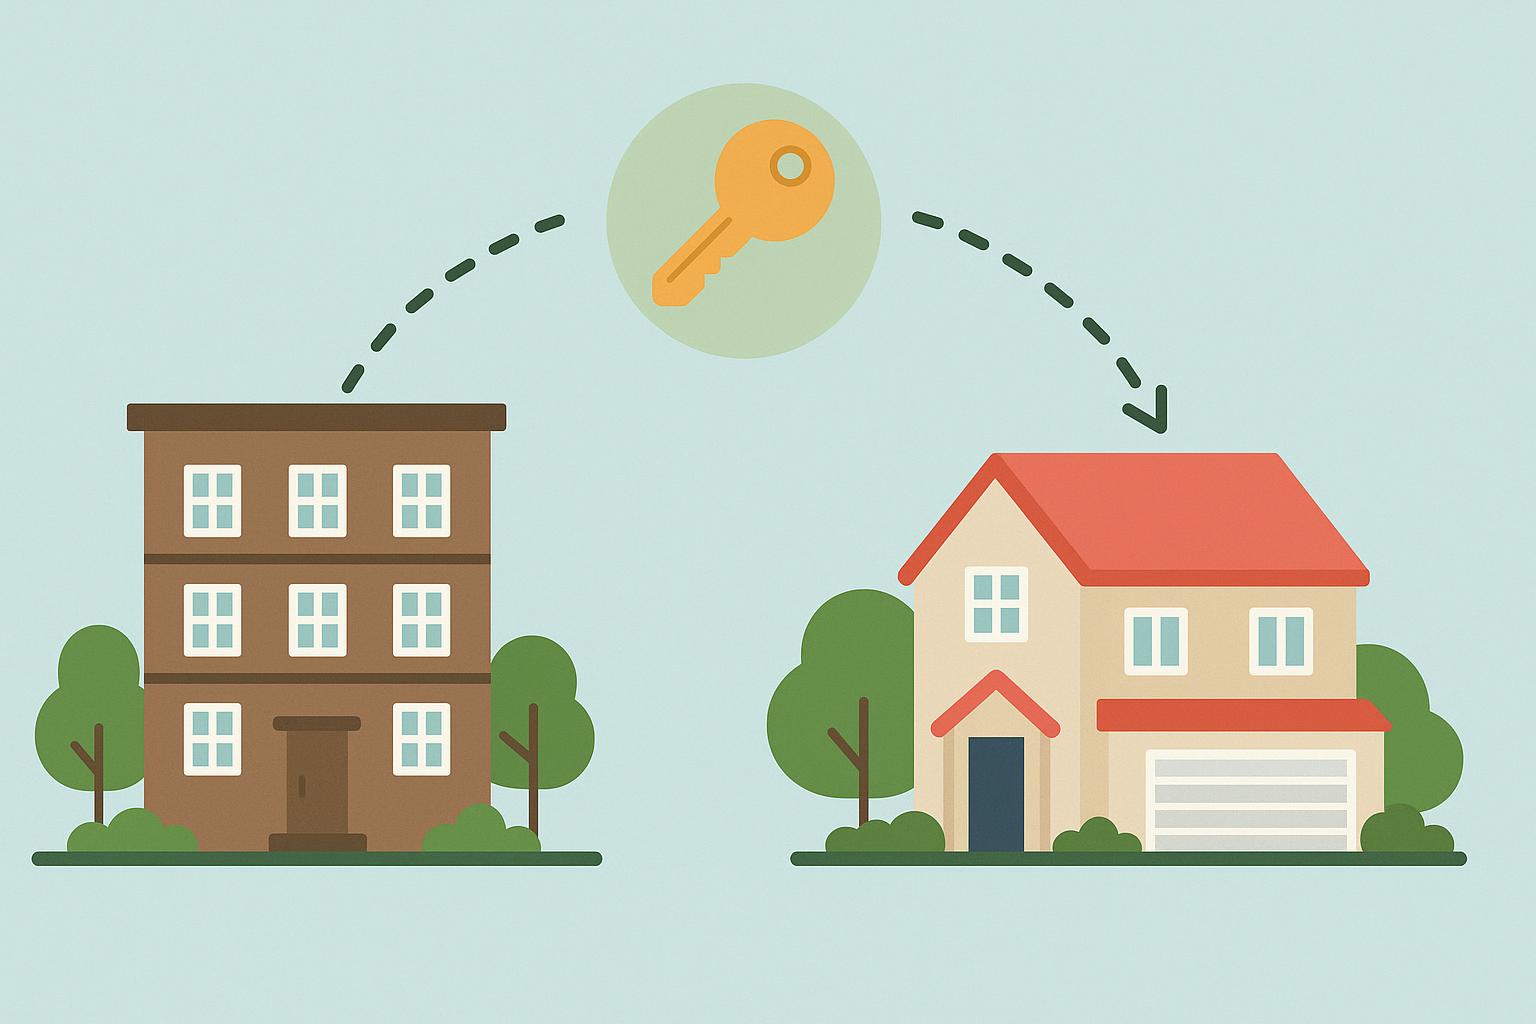
Renting and buying often feel like separate stages. This matters because many first-time buyers spend years renting before purchasing. A program credit changes the question from whether a renter has paid rent to whether those rental months can support a qualifying purchase.
Drewlo Holdings, an Ontario rental housing provider, connects those stages for eligible residents through a program tied to a later home purchase.
Drewlo handles the rental side. The Ironstone Building Company provides the Ironstone purchase path connected to the program. The practical question is how renting with Drewlo may fit into a future buying plan, not whether renting alone makes someone ready to buy.
The connection comes through Drewlo’s Rent.Save.Own. program. Under the program, a Drewlo renter may receive $400 for each month rented, up to $15,000, toward a new home or townhome from Ironstone. That gives the renter a defined purchase credit tied to the program rather than making rent payments themselves a form of homeownership savings.
The program credit needs careful interpretation. It is a voucher based on the renter’s Drewlo tenancy that may be applied toward a qualifying purchase. It is not cash that the renter can withdraw or use elsewhere because Ironstone states that the voucher has no cash value. The renter should understand that restriction before including the credit in a purchase plan.
Timing affects how much value the renter can build. Because the credit grows month by month and stops at a stated cap, the length of the tenancy matters. A renter who plans to buy soon may receive a smaller credit than someone whose rental period allows the credit to grow closer to the maximum.
The purchase destination also matters. For the Ironstone route, the credit applies to an eligible Ironstone purchase, so the renter should compare the homes available through Ironstone with the type of property they want and what they can afford. If those available options do not suit the renter’s purchase plan, the Ironstone credit may be less useful even when the renter otherwise qualifies for the program.
Once a renter sees a possible Ironstone fit, the next question becomes whether the buyer can qualify for that purchase. Mortgage preapproval remains a separate step, and preapproval does not guarantee final mortgage approval. A lender may review income, employment, debts, assets, identification, and proof of funds, and may run a credit check before deciding how much a buyer may borrow. That review can shape the buyer’s price range before the rent credit becomes useful in a specific transaction.
The down payment creates its own planning question. The minimum amount usually depends on the purchase price, and a smaller down payment may bring mortgage loan insurance costs. A renter should understand that calculation early because the chosen home price affects how much cash the buyer must bring to the purchase.
Closing and unexpected costs add another layer to the budget. Buyers may face home inspection fees, legal fees, property tax adjustments, title insurance, moving costs, and repairs outside the advertised home price. These costs can affect move-in planning even after the buyer has selected a home and arranged financing.
Before relying on the program, a renter should confirm how qualifying rental months are counted, who qualifies, whether the purchase must be a direct sale, when the voucher expires, whether it can be transferred, and whether it has cash value. Ironstone’s published terms already state that the offer is for leaseholders, applies to direct sales, expires on the last day of tenancy, is non-transferable, and has no cash value.
In practice, the credit is most useful when the renter’s program eligibility, financing, purchase timing, and available Ironstone property all support the same transaction.
About Stuart Hansen
Stuart Hansen is a Los Angeles-based real estate executive who serves as vice president of Marquee Asset Management, LLC, part of the Ontario, Canada-based Drewlo family of companies. He oversees Marquee’s domestic and international operations and leads Shelter Asset Management, a real estate development and investment consultancy. Earlier in his career, he served as international investment manager for Drewson Capital Corp and held marketing and sales leadership roles with Clarion Hotels in Canada. He holds a business administration degree from the University of Western Ontario.